Diamondback Energy’s Q3 2026 update highlights disciplined Permian development, expanding Barnett activity and autonomous artificial-lift optimization. Our YTD drilling data tracks 458 wells across nine Texas counties, showing where activity is concentrated and which contractors and rigs are supporting the program.
Diamondback Energy’s Q3 2026 earnings call
- Financial results: The transcript reports earnings per share of $5.86 and revenue of $5.43 billion, up 38.4% year over year, both above analyst expectations.
- Capital discipline: Management discussed a reinvestment rate of approximately 30%–32%, emphasizing free cash flow, debt reduction, dividends and opportunistic share repurchases.
- Drilling outlook: The preliminary operating framework is 19–20 rigs and five frac crews, supporting some organic production growth. Formal 2027 guidance is expected in February.
- Permian focus: Diamondback intends to remain focused on the Permian, expanding opportunities through drilling, minerals, midstream infrastructure and power projects.
- Barnett development: The company is moving its Permian Barnett formation program toward full-field development. Four or five full-section developments were expected to come online over the following three to four months.
- Well cost improvements: Longer laterals, shared infrastructure and faster drilling are expected to improve Barnett economics. Management highlighted $850–$900 per lateral foot as an important range for competitive capital efficiency.
- Improved oil recovery: Current recovery is approximately 10% of oil in place. Management believes 11% could be achievable within a few years, while larger improvements remain longer-term opportunities.
- Chemical trials: Diamondback is testing surfactants and other recovery treatments. A one to two percentage point increase in recovery could potentially add 50,000–100,000 barrels per well, although field results remain variable.
- Recovery investment: Management discussed approximately $50 million–$100 million for recovery initiatives within an overall capital budget exceeding $4 billion.
- AI and artificial lift: Autonomous plunger-lift optimization is reducing manpower requirements and compression use while improving production and limiting downtime. Deployment to approximately 1,000 remaining plunger-lift wells was expected within months.
- Field productivity: Drone technology and automation are intended to help personnel identify problems earlier and spend more time fixing issues.
- Natural gas strategy: Management expects LNG and power demand to increase the value of Permian gas over the next decade. Pipeline capacity and downstream partnerships are central to accessing these markets.
- Bryant Ranch power project: Management described the site as shovel-ready, with equipment secured and water and gas arrangements prepared. Final agreements were still being completed.
- Minerals and acquisitions: Viper remains an important avenue for mineral acquisitions. Management sees large corporate acquisitions as more difficult amid commodity-price volatility.
- OFS implications: The discussion points to opportunities in artificial-lift automation, production chemicals, recovery treatments, deep drilling, shared facilities, gas infrastructure and power development, alongside continued pressure on service costs and execution efficiency.
Wells drilled YTD 458, with Activity Dates from January 2 to November 2, 2026.
Record count by Province/State
Province/State Records Share Texas 458 100.0% Total 458 100.0%
Record count by play/basin
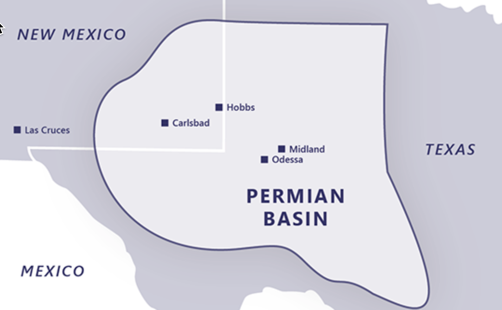
All 458 records fall within the greater Permian Basin. The county-based regional grouping below is approximate because geological boundaries cross counties. Andrews and Ector are shown separately to avoid assigning their eastern wells automatically to the Central Basin Platform. rrc.texas.gov
Play/Basin grouping Counties included Records Share Permian – Midland Basin Midland, Reagan, Martin, Glasscock, Howard, Upton 401 87.6% Permian – Midland Basin / Central Basin Platform boundary counties Ector, Andrews 56 12.2% Permian – Delaware Basin area Pecos 1 0.2% Total 458 100.0%
County detail
County Records Midland 130 Reagan 116 Martin 88 Glasscock 49 Ector 45 Howard 14 Andrews 11 Upton 4 Pecos 1 Total 458
Contractors ranked by record count
Only eight named contractors appear in the file; seven records have no contractor or rig reported.
Rank Contractor Records 1 Ensign 214 2 Latshaw 69 3 Independence 65 4 Nabors 59 5 NorAm 40 6 Pinnergy 2 7 Precision 1 8 Savanna 1 — Not reported 7 Total 458
Top 10 contractor-and-rig combinations
Rank Contractor and rig Records 1 Ensign 773 26 2 Ensign T140 25 3 Ensign T141 25 4 Latshaw 14 25 5 Ensign T134 24 6 Latshaw 19 23 7 Ensign 775 22 8 Independence 306 21 9 Latshaw 9 21 10 NorAm 30 21
Midland, Reagan and Martin counties account for 334 records, or 72.9% of the total. Ensign accounts for 46.7% of all records. Rig rankings represent YTD well records associated with each rig, rather than currently active rig counts.
Author: phinds